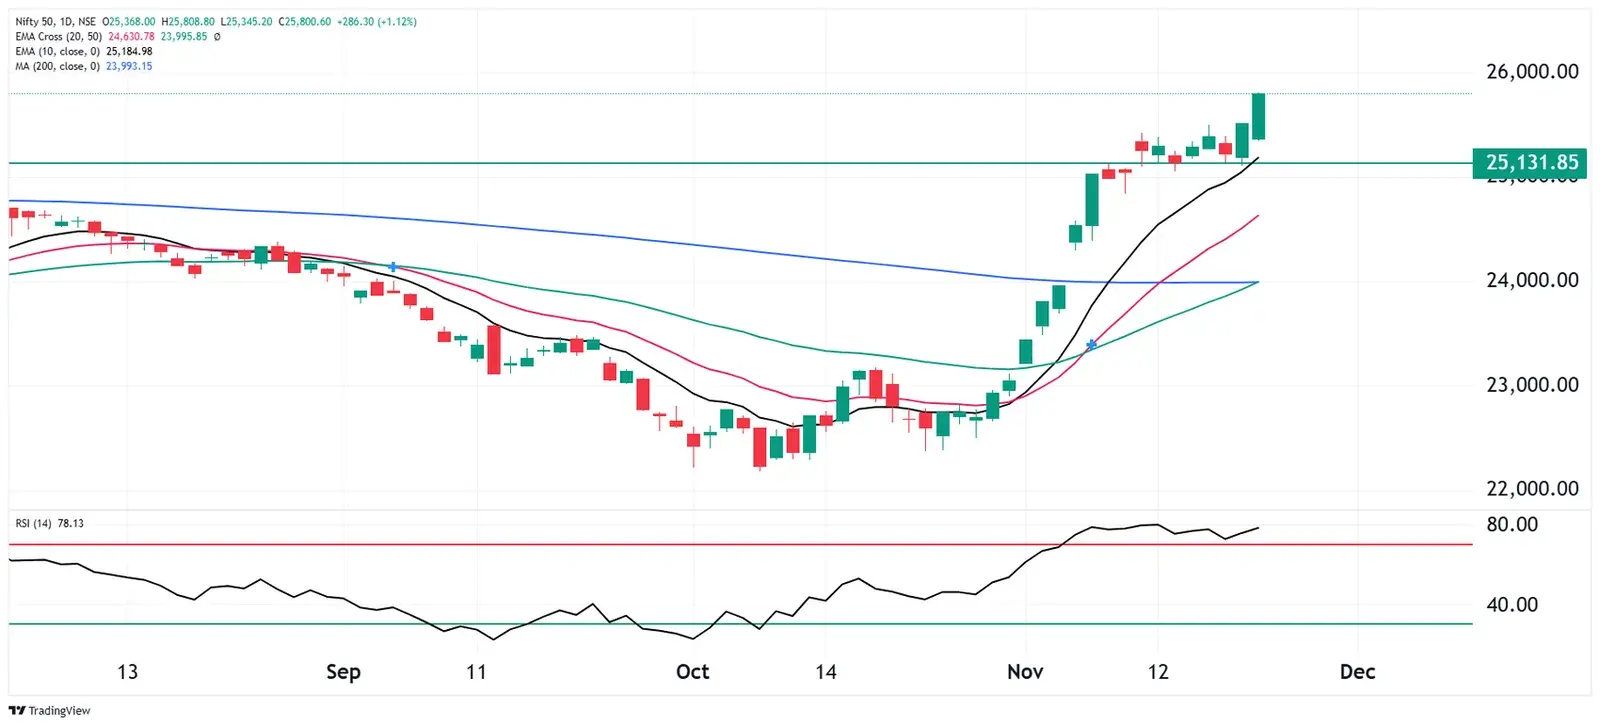
Indian equities gained for a fourth consecutive week. The NIFTY50 rose 2.6%, to 25,800, while the Sensex added 2.8%, to 83,919. Foreign buying, lower crude prices and rotation toward India as global AI stocks weakened supported sentiment.
Profit-taking interrupted the advance on Wednesday, on Friday, the NIFTY50 recovered from an early decline to close at a nine-month high. Banks, Realty and IT supported that session’s recovery.
The gains were concentrated in larger companies. The Nifty 500 rose 1.4%, the Nifty Midcap 150 added just 0.3% and the Nifty Smallcap 250 declined 0.86%. This divergence means the headline-index advance did not translate into similar returns across market sizes.
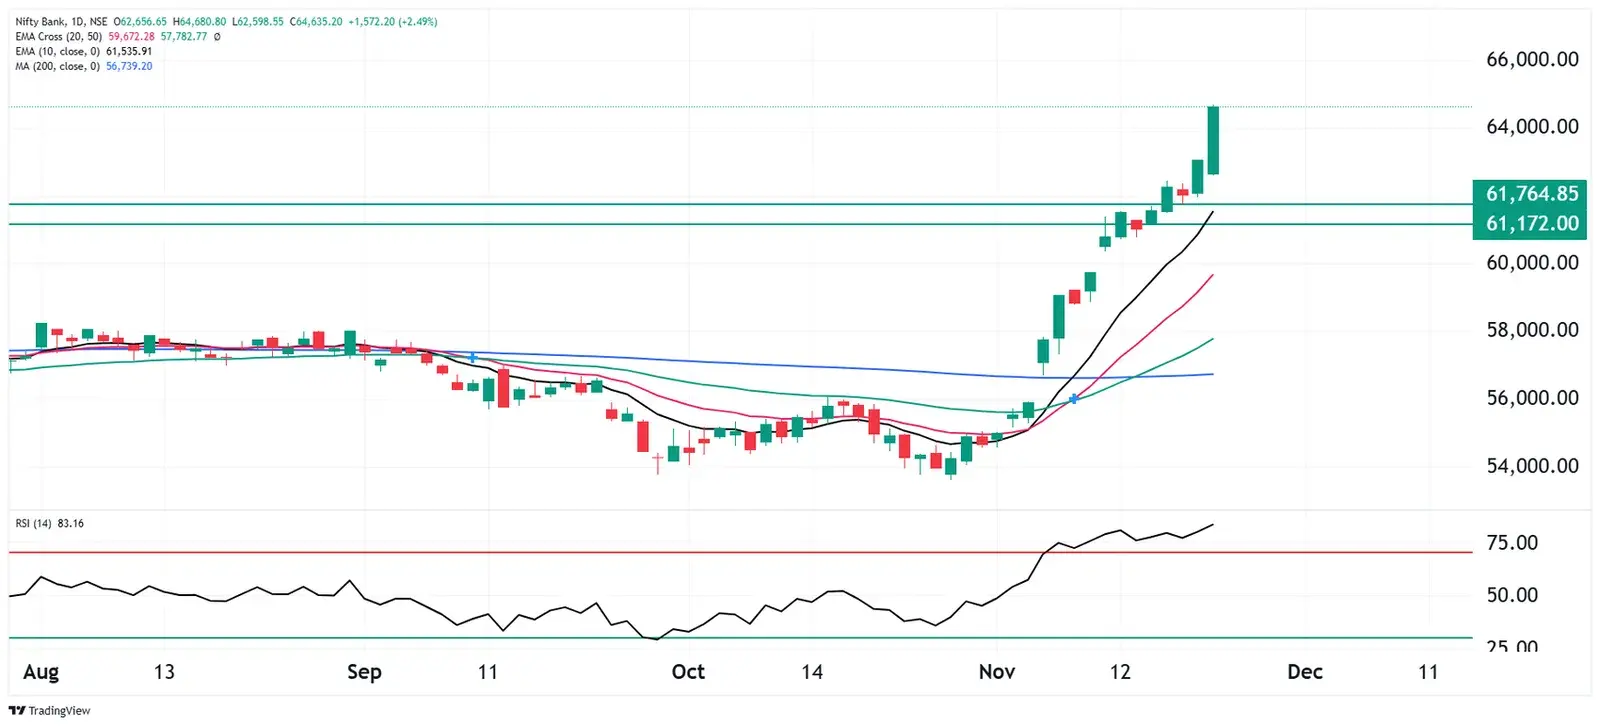
Banks were the main leaders, Nifty Bank rose 5.9% all ahead of the NIFTY50’s 2.61% gain. Foreign interest, credit growth and improving asset quality supported the banking theme. Financial services (+3.6%), FMCG (+3.6%) and Auto (+3.0%) also outperformed. Metals (-2.9%), Capital markets (-1.9%) and IT (-1.9%) were the weakest sectors.
️Spotlight: Banks rallied as renewed foreign investment, combined with improving loan growth and earnings expectations, boosted confidence. Investors rotating away from global AI stocks returned to Indian banking heavyweights. Market experts cited stronger credit demand, new foreign-currency deposits that improved funding availability and a reduction in bad loans.
Additionally, the margin outlook is better as lending rates adjust to RBI rate increases. These operating trends, alongside lower crude prices and more attractive valuations following earlier sell-offs, supported buying across private and public-sector lenders. Rally drivers: foreign buying and earnings outlook. The Nifty Bank index rose by 5.9% to reach 64,635 by the end of the week on 20 November, touching an intraday record of 64,680. Among the constituents, PNB, Axis Bank, SBI, HDFC Bank and ICICI Bank advanced by between 3% and 8%.
️Key events in focus: In India, November flash manufacturing, services and composite PMIs are due on Monday, November 23. The November monthly derivatives expiry moves to Monday, November 23 because Tuesday is a market holiday.
In the United States, the main data cluster is Wednesday, November 25. Both the second estimate of third-quarter GDP and PCE inflation reading is expected to rise 0.3% month on month and 3.8% year on year. Core PCE is expected at 0.3% month on month and 3.2% year on year. Meanwhile, GDP forecasts differ modestly across calendars at 3.4-3.5% annualised growth, versus the initial 3.4%.
Mark your calendars: Indian markets will be closed on Tuesday November 24 for Guru Nanak Jayanti. Trading will resume on November 25. US equities will be closed for Thanksgiving on November 26 and end the November 27 session early. Holiday participation could be lighter just as markets digest Wednesday’s releases.
️Crude oil: Oil declined for a third consecutive week as returning supply and inventory builds outweighed geopolitical concerns. January Brent settled at $92.57 a barrel, down 3.4% for the week. The expiring December WTI contract finished at $83.98, down 5.2%. Expectations of a supply surplus pressured prices, while Friday’s recovery reflected concern about renewed hostilities and position adjustments before Thanksgiving. Houthi attacks on Saudi infrastructure, tanker incidents around Hormuz and damage to Russian refineries remain supply risks.
Market breadth
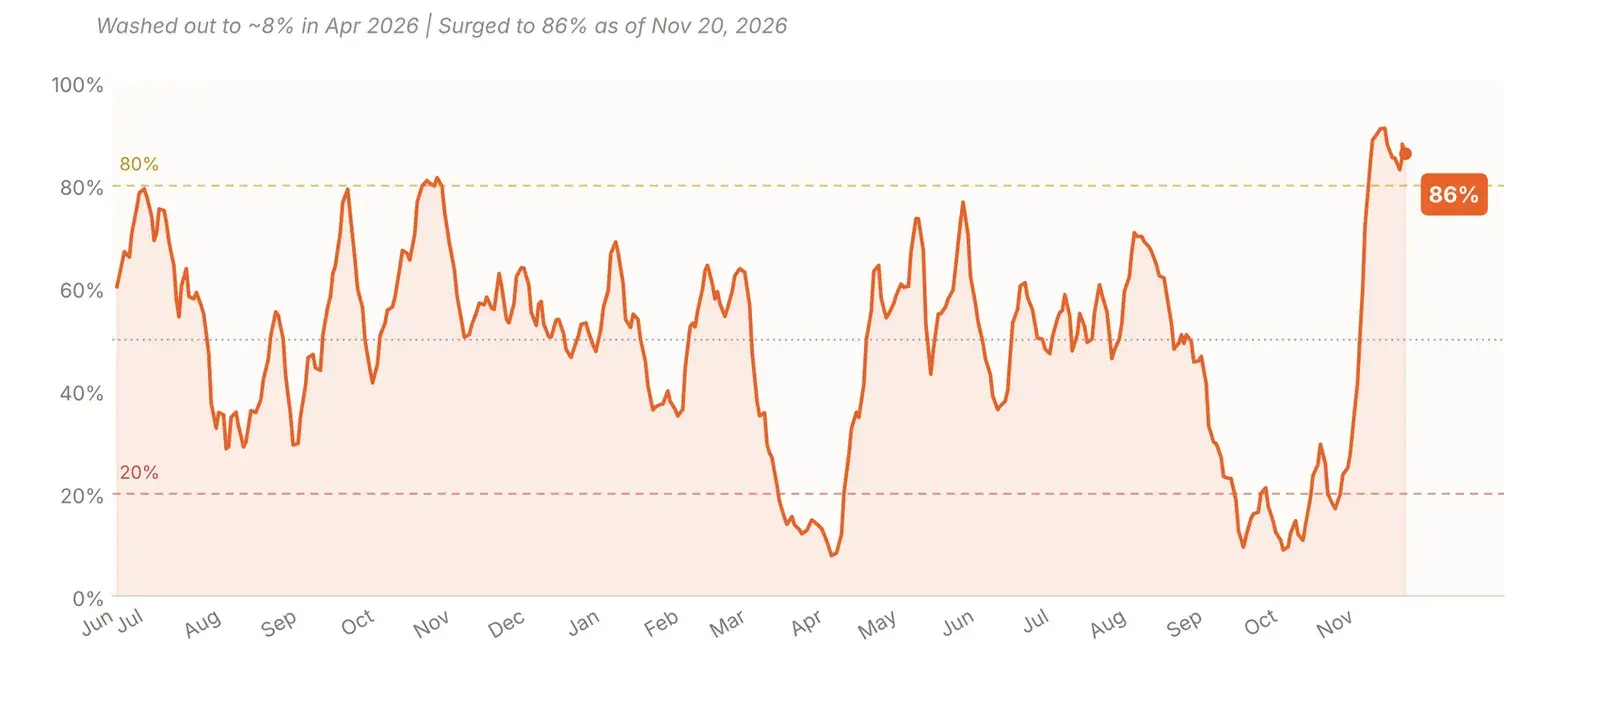
NIFTY50 breadth improved to 86%, or 43 of 50 stocks above their 50-day moving averages, on 20 November, compared with 84% a week earlier. The two-percentage-point rise supports the benchmark’s advance, with participation remaining above the chart’s 80% marker. Strength was concentrated in larger companies.
Foreign investors positioning
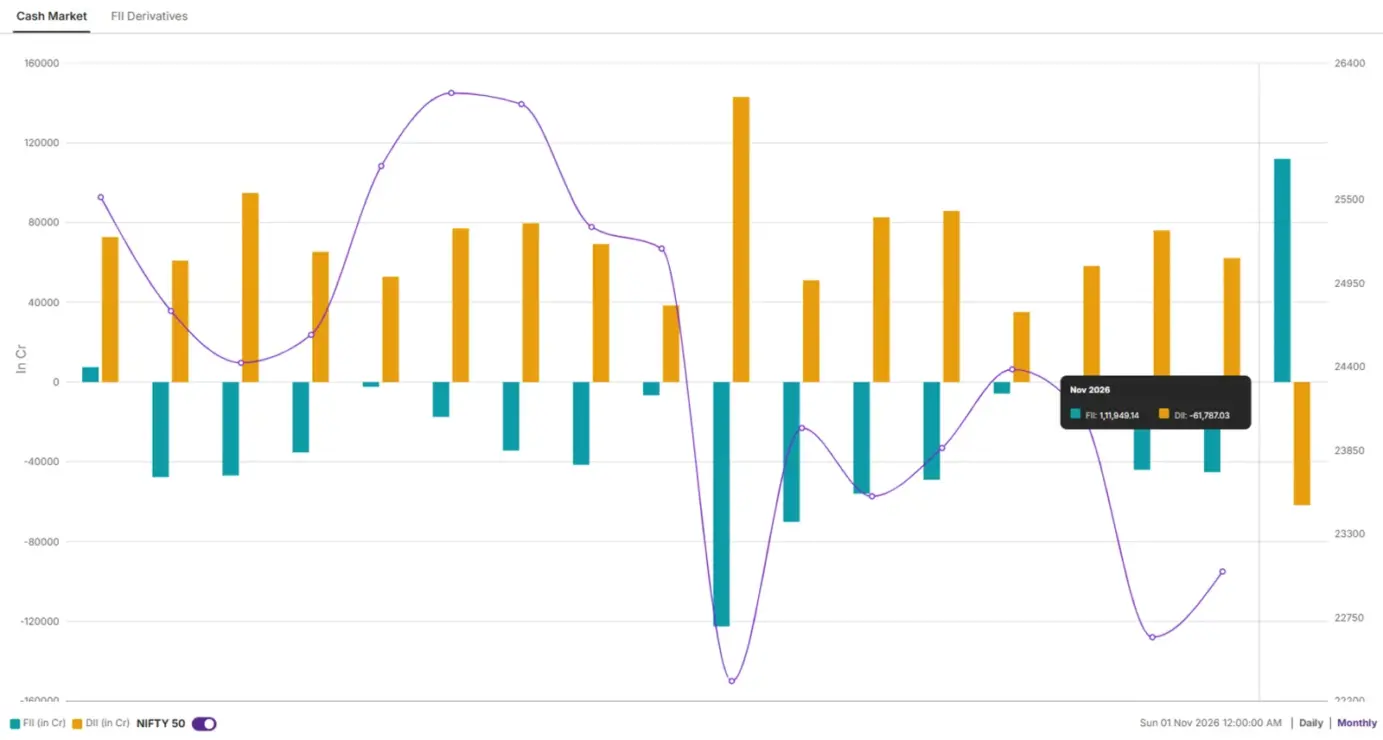
FIIs bought a net ₹32,646 crore in the cash market during 16-20 November, taking November month-to-date net buying to ₹1,11,949 crore. Meanwhile, DIIs sold a net ₹12,698 crore over the week, taking November month-to-date net sales to ₹61,787 crore. Foreign buying more than offset domestic selling, leaving combined net cash purchases of ₹19,948 crore for the week.
NIFTY50 outlook
The NIFTY50 broke above its recent consolidation range and closed at Friday’s high. The index remains above its rising 10-day and 20-day EMA, keeping the broader structure bullish. However, the RSI at 78.13 remains below its earlier November peak despite the higher index level. This developing bearish divergence and overbought reading suggest that momentum is not fully confirming the price advance.
If the NIFTY50 sustains above Friday’s high of 25,808, then the next level in focus is the psychological 26,000 mark. If it closes below Friday’s low of 25,345, then a pullback towards the 25,132-25,185 support zone, marked by the horizontal support and 10-day EMA, becomes more likely.