Klarna Group posted better-than-expected Q3 revenue on Tuesday, but missed earnings expectations, while Affirm beat top-line Q1 results earlier this month and also missed EPS forecasts.
- Klarna reported a loss per share of $0.19 on Q3 revenue of $1.009 billion.
- Affirm reported Q1 adjusted EPS of $0.47 on revenue of $1.26 billion.
- According to Koyfin data, Wall Street sees an upside of about 35% on KLAR stock over the next 12 months, while it sees an upside of over 61% on AFRM stock.
Klarna Group plc (KLAR) reported its third-quarter (Q3) print on Tuesday, posting better-than-expected revenue and sending shares up nearly 5% at close.
Meanwhile, Affirm Holdings Inc. (AFRM) reported first-quarter (Q1) results on Nov. 5, beating top-line results but missing Wall Street expectations on earnings per share.
With both companies having reported quarterly results, the question now is which stock is the better bet in the current market.
Klarna Posts Strong Revenue, Reiterates Outlook
Klarna reported Q3 revenue of $1.009 billion, up 12% year-over-year, beating analyst estimates. Meanwhile, net losses narrowed to $65 million from $95 million a year earlier, while adjusted EPS of -$0.19 was wider than Wall Street expectations of -$0.13.
However, the company’s gross merchandise volume (GMV) rose 10% to $36.1 billion, driven by 24% growth in the U.S. Transaction margin dollars increased 32% to $371 million, while adjusted operating income improved by $35 million to $21 million.
Klarna’s revenue growth was boosted by Klarna Card volume more than doubling to $4.5 billion and subscription revenue surging 500% to $43 million.
The flexible payments provider reiterated its full-year 2026 guidance, forecasting revenue of $4.08 billion to $4.16 billion and GMV of $149 billion to $151 billion.
Affirm’s Earnings More Than Doubled Amid Growing Card Adoption
Affirm reported Q1 adjusted EPS of $0.47, missing analyst estimates, but more than doubling from $0.23 a year earlier. The company reported revenue of $1.26 billion, up 32.15% year-over-year.
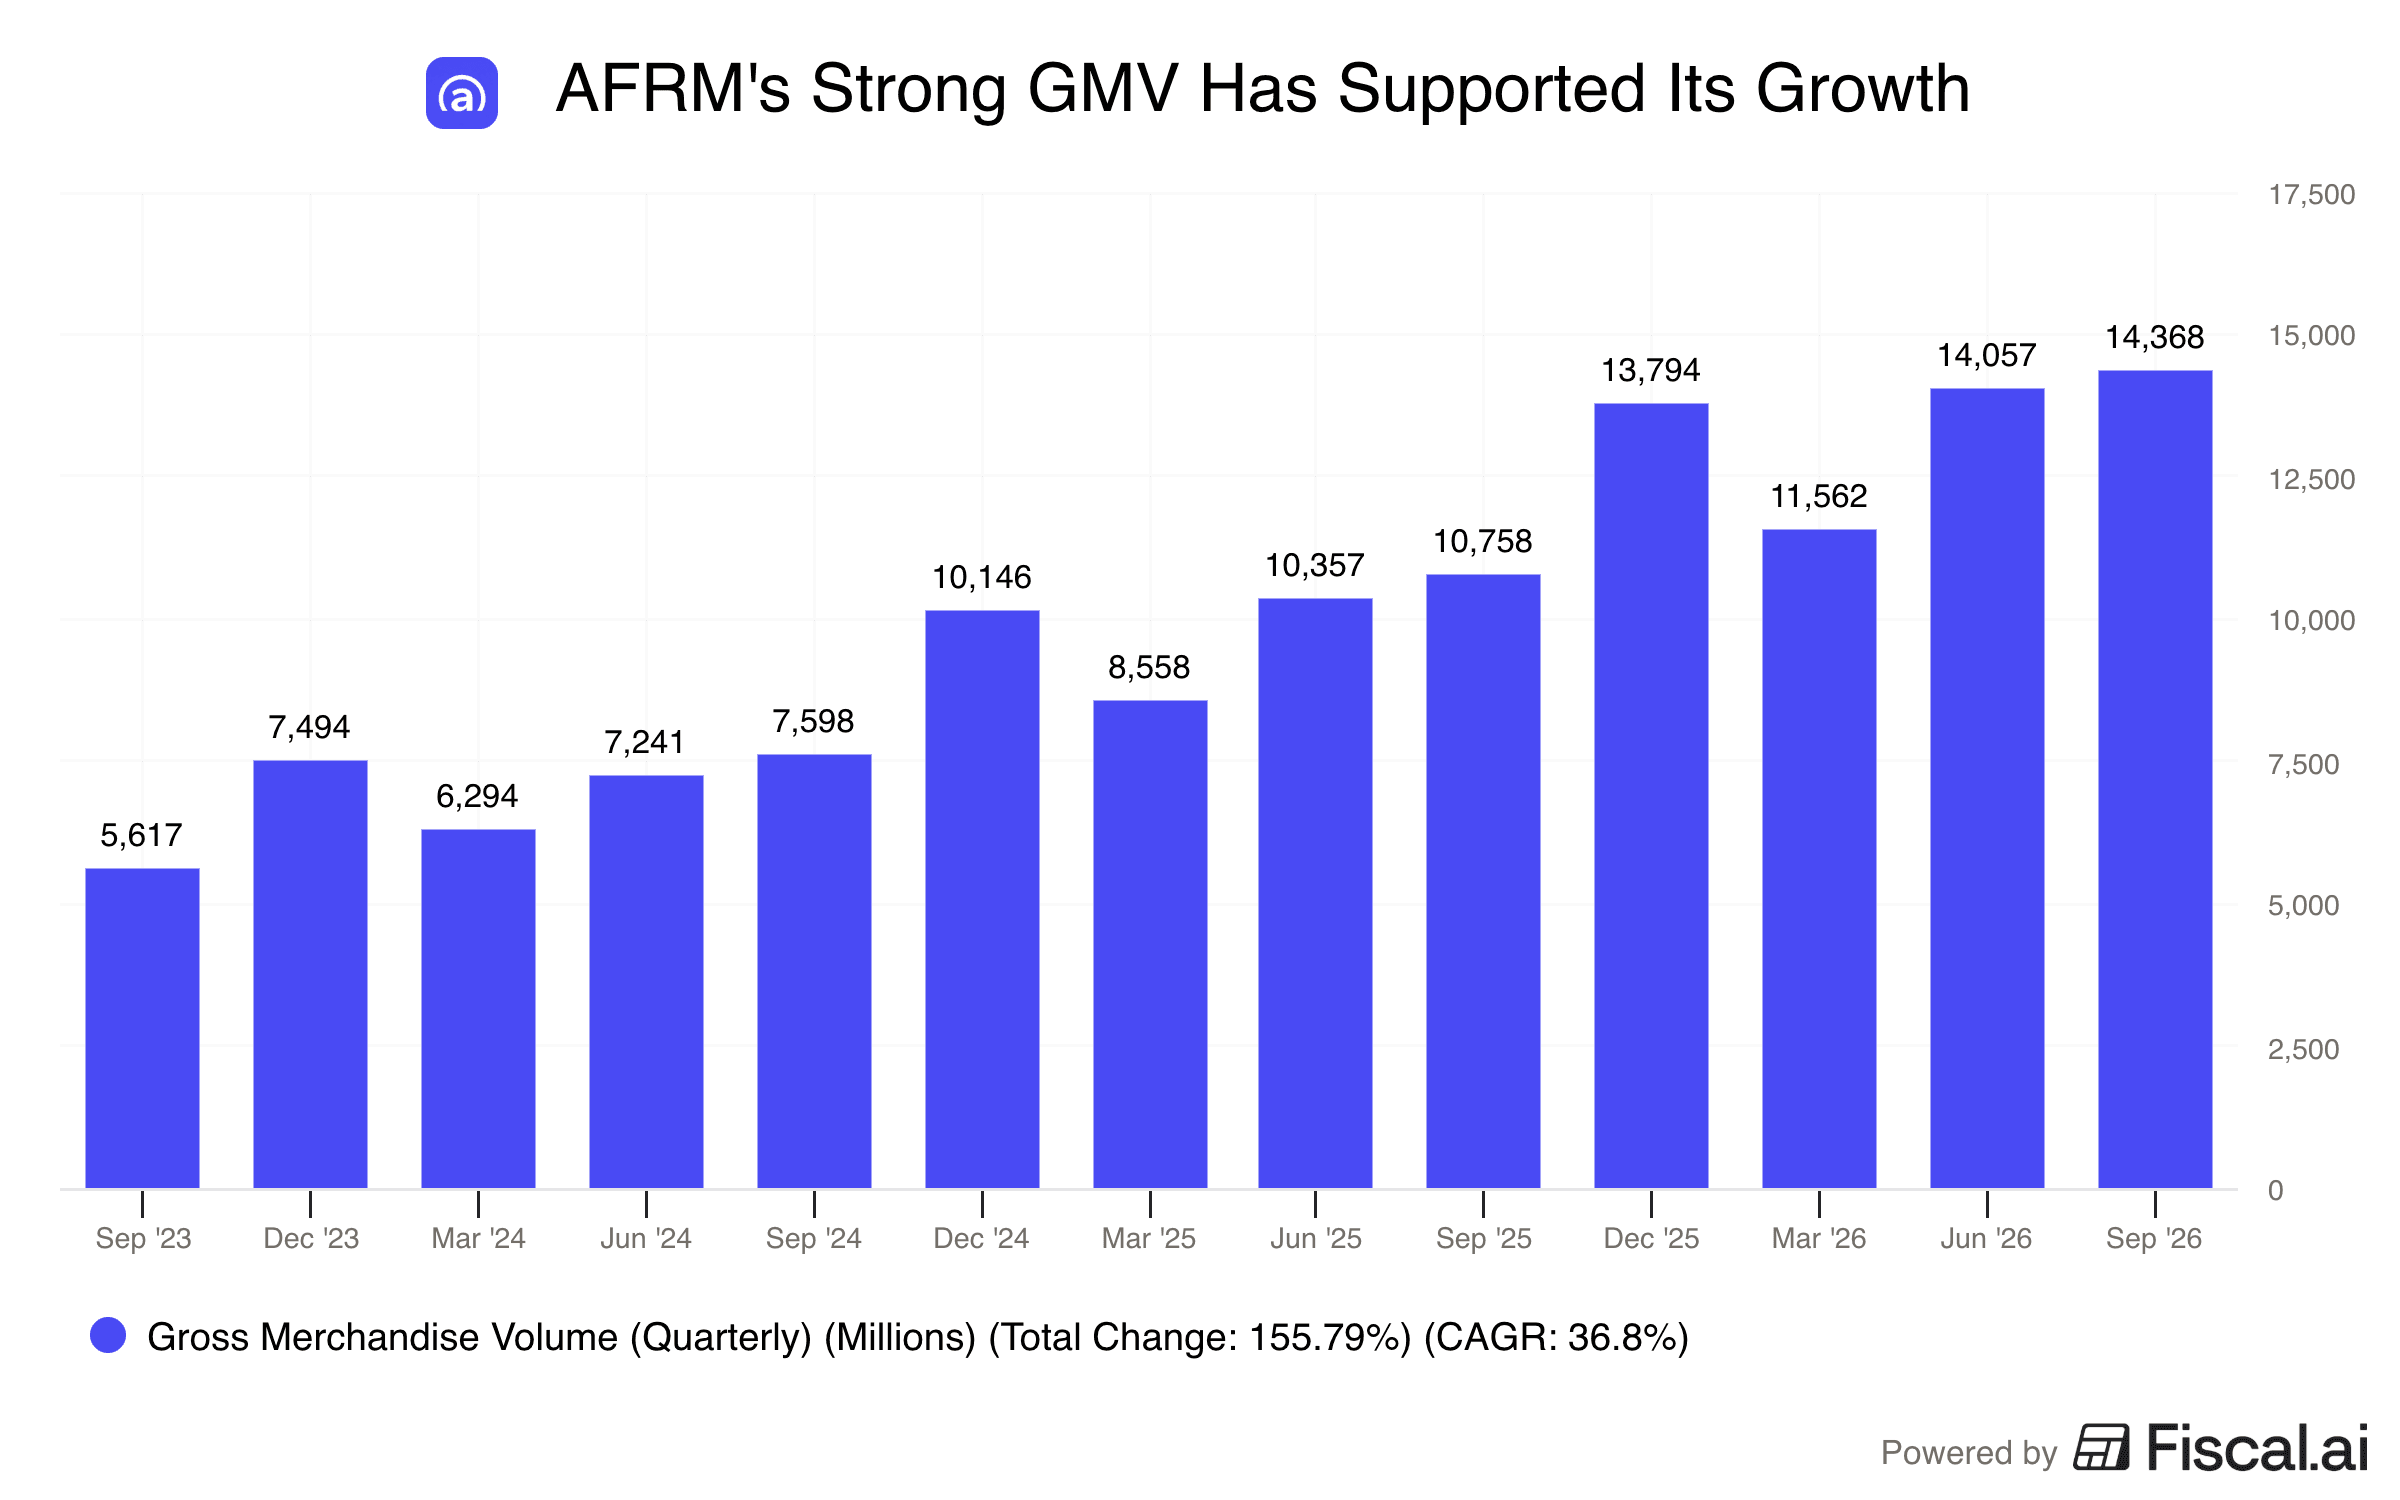
Despite the earnings miss, the company continued to deliver strong growth, with GMV expanding at an annual rate of more than 30%, supported by expanding card offerings and zero-interest financing programs.
Its GMV reached $14.4 billion in the quarter, up 34% year-over-year, while Affirm Card GMV surged 117% to $3.3 billion, accounting for roughly 23% of total volume with 6 million active cardholders.
Affirm projects revenue between $1.435 billion and $1.465 billion for the upcoming quarter.
Wall Street Stance On KLAR, AFRM
Following its Q3 results, Freedom Capital analyst Lemar Clarke raised Klarna’s price target to $20 from $17 and maintained a ‘Buy’ rating on the shares, implying an upside of over 40% from its last close.
The analyst noted that the company beat its Q3 guidance on every line, with gross merchandise volume rising and U.S. GMV accelerating to close to 30% year-over-year.
According to Koyfin data, the 12-month average price target on KLAR stock is $19.24, implying an upside of nearly 35% from the stock’s last close.
Of the 25 analysts covering the stock, 11 have a ‘Buy’ or higher rating, and 14 have a ‘Hold’ rating.
Meanwhile, on Tuesday, Truist lowered its price target on Affirm to $86 from $88 and maintained a ‘Buy’ rating. The revised target still implies an upside of more than 44% from its last close.
The firm said the upper end of Affirm’s second-quarter gross merchandise volume growth guidance of 30%-32% year-over-year was in line with its estimate entering the print. However, Truist is increasing its Q2 estimate to 35% given commentary that GMV growth had been running in the high 30s in October, which is in line with normalized GMV growth in Q1 after excluding factors that are not expected to continue, the analyst tells investors in a research note. The firm added that its reduced price target reflects lower target multiples for most fintech lenders.
According to Koyfin data, the 12-month average price target on AFRM stock is $95.75, implying an upside of over 61% from the stock’s last close.
Of the 36 analysts covering the stock, 29 have a ‘Buy’ or higher rating, and seven have a ‘Hold’ rating.
Retail Stance On KLAR, AFRM Stocks
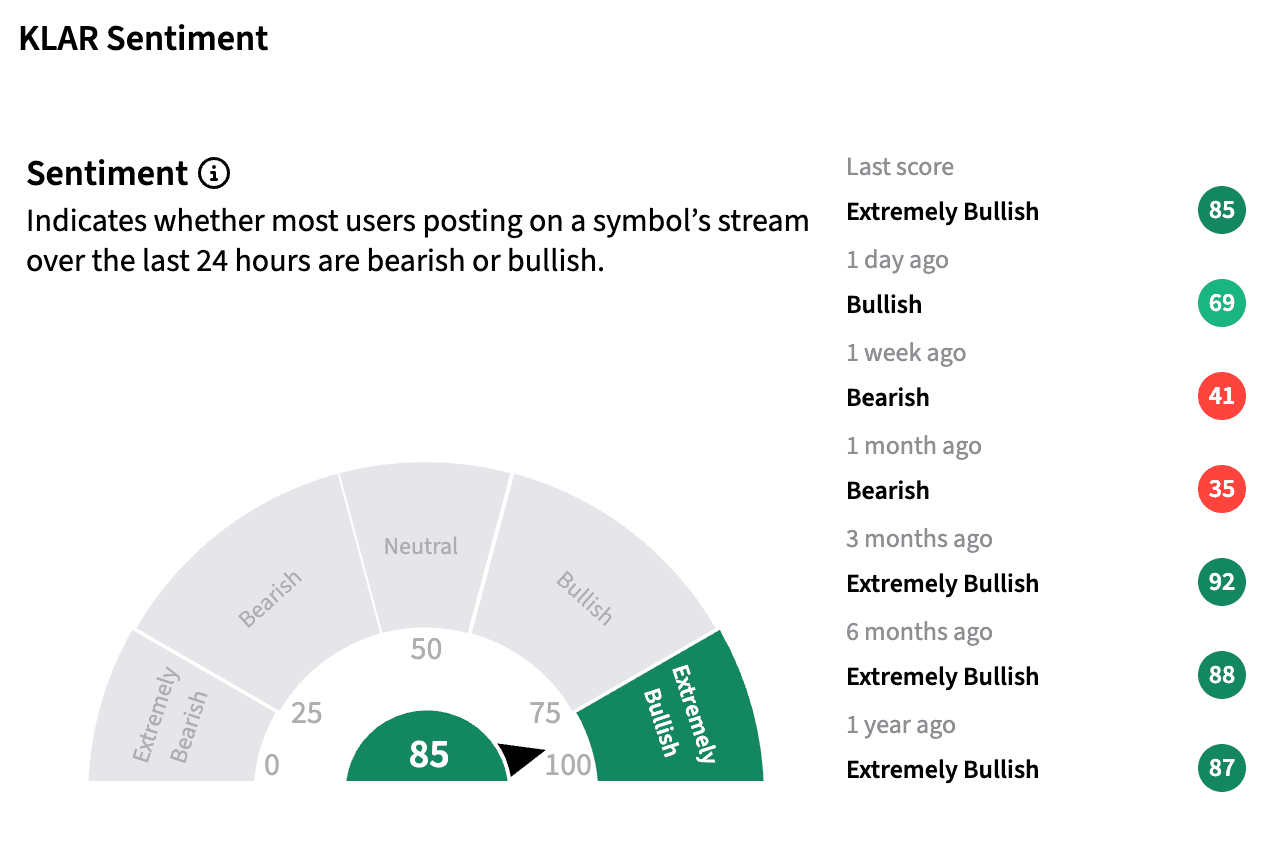
On Stocktwits, retail sentiment around KLAR stock improved from ‘bullish’ to ‘extremely bullish’ over 24 hours amid ‘extremely high’ message volumes.
One user said, “$KLAR good day, a little reassurance. 2027 gonna be the real interesting deal.”
Another user said, “$KLAR back to $20+. The world economy is a giant growing bubble that runs on debt/credit and this company is everywhere.”
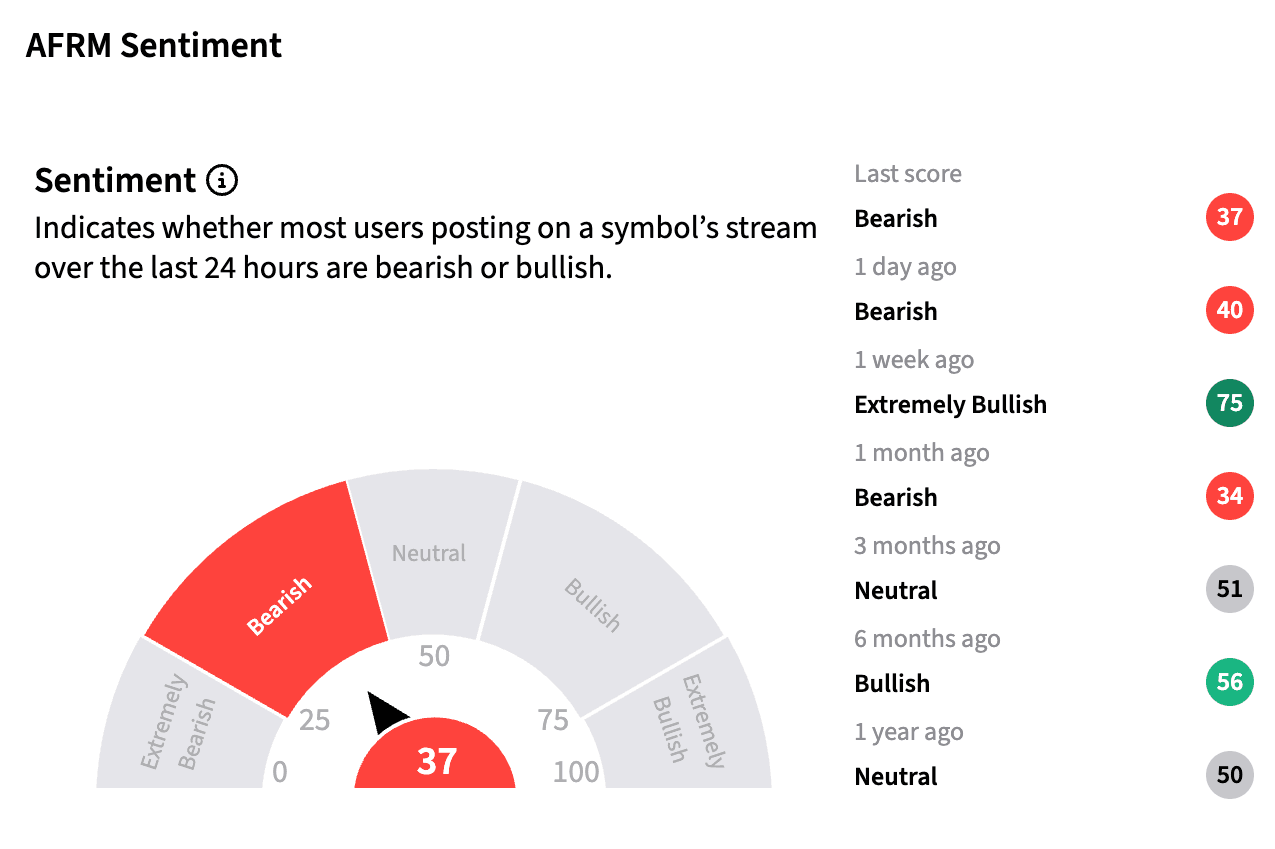
Meanwhile, retail sentiment around AFRM stock was ‘bearish’ at the time of writing amid ‘normal’ message volumes.
One user said, “$AFRM affirm lives on the household side of this economy, financing basics at checkout. seems like an ai boom built on capex charts looks different next to a delinquency chart.”
However, another user said, “$AFRM down ~5% to ~$59.70. Truist still says Buy, trimmed its target to $86 from $88 on lower fintech multiples, and noted GMV growth ran in the high 30% range in October. That’s a multiple problem, not a business problem imo. Bullish.”
KLAR stock is down more than 50% year-to-date, while AFRM stock has lost about 20% of its value during the same period.
For updates and corrections, email newsroom[at]stocktwits[dot]com.<